By Robert Balgac, Founder, Black Swan Insurance Group | October 9, 2026
If you earn $150K+, you have maxed the 401(k), you are past the Roth phase-out, and you have decided a max-funded indexed universal life policy belongs in your plan, the work ahead is sequencing. Not shopping. Sequencing.
Because the single most common way this goes wrong is doing the steps in the wrong order — picking a premium first, then reverse-engineering a death benefit to accommodate it. That produces a contract optimised for a number rather than for a need, and it tends to fail quietly, four or five years in, when income changes and the schedule no longer fits.
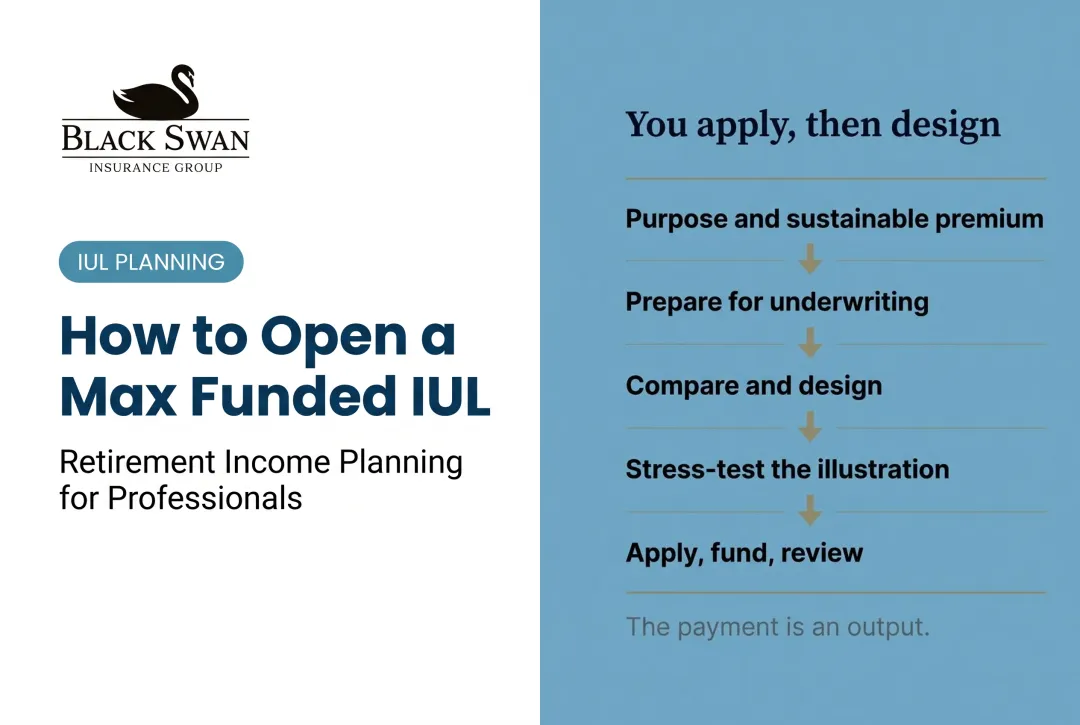
The short answer: Define the purpose, size the death benefit your household or business actually needs, compare at least two designs across multiple carriers, complete underwriting before you commit to a premium, fund at a level you can sustain in a weak year, and review it annually against the original illustration. "Max funded" is not a dollar figure — two people with identical incomes can land on very different targets.
This is still life insurance first. The death benefit has to make sense on its own before cash value accumulation enters the conversation.
Key Takeaways
- Max-funded IUL is a funding strategy within a policy, not a separate product
- Put the death benefit need first — cash value efficiency never overrides protection
- Review the 7-pay test, MEC rules and carrier charges before applying
- Handle retirement accounts, emergency savings and debt priorities first
- Treat illustrations as projections, and compare the guaranteed column too
- The order of the steps matters as much as the steps themselves
Step 1: Define the Purpose and Confirm Basic Suitability
Identify what the policy must do. Permanent death benefit protection, supplemental retirement income, tax diversification, business liquidity, legacy planning. Most buyers have a combination; one usually drives the design.
Before setting any premium target, take stock of income stability and genuinely surplus cash flow, emergency reserves and existing life insurance, current retirement contributions and debt, and how many years you can realistically fund.
A max-funded design is not a good fit for everyone. If you need short-term liquidity or cannot reliably commit over a long horizon, this is not the right tool yet — and "yet" is doing real work in that sentence.
Step 2: Establish the Protection Target Before the Premium
Separate the death benefit your family or business actually needs from the amount you could push toward cash value. Do not let the pursuit of cash-value efficiency argue you into less coverage than you need.
Factor in dependants and income replacement, mortgage balance, education costs, estate goals, business succession obligations, and any term or permanent coverage already in force.
If the minimum non-MEC death benefit does not cover your household's protection gap, a term rider or a higher permanent death benefit can close it. LIMRA's 2025 Insurance Barometer found that 40% of U.S. adults say they need life insurance or more of it. Protection gaps are common even among people who are otherwise financially prepared.
Step 3: Compare Carriers and Demand Two Designs
Carriers do not price the same risk the same way. Request illustrations from multiple suitable carriers and compare policy charges, guaranteed values and non-guaranteed assumptions; index strategies, caps, participation rates and spreads; loan provisions and surrender schedules; available riders and financial-strength ratings.
Ask for at least two designs: one with a minimum death benefit optimised for your planned premium, and a "headroom" design that leaves room for extra funding in an unusually strong income year. The second design is the one people skip, and it is the one that saves you when a bonus arrives and the first design has no capacity left to receive it.
A side-by-side comparison of real illustrations beats guessing. No brokerage can promise approval or guarantee performance.
Step 4: Apply, Underwrite, Then Finalise the Funding
Underwriting requires documentation: financial information, health history, prescription records, existing coverage, income verification and identification. What a carrier asks for varies by policy size and age.
Your age, health classification, tobacco use, occupation and financial justification all affect eligibility, premium capacity, available death benefit and overall policy efficiency. This is why you do not fix a premium before underwriting finishes — the offer you receive may not be the offer you modelled.
Before signing and funding, confirm the planned premium, payment schedule, death benefit option, riders, index allocations and non-MEC limit in writing. A verbal summary is not a contract term.
Step 5: Fund and Monitor
Automate only a premium you can sustain under conservative cash-flow assumptions, not your best year. Policy flexibility is not permission to stop funding without understanding the consequences.
Each year, track cash value, charges and crediting rates; caps, participation rates and loan balances; and surrender values alongside the policy's ability to stay in force. Involve tax or legal advisers before taking loans, reducing premiums, changing benefits or making large additional payments.
This is not set-it-and-forget-it. It is design-it, fund-it, review-it.

The Ultimate IUL Blueprint
Before you start the sequence, the Blueprint covers what the design has to survive: funding levels, caps and charges, the MEC line, loan timing, and what to demand from an illustration before you sign it.
What the Critics Get Right
The fair criticism of max funding is that the phrase itself invites a bad instinct. "Max" sounds like optimisation. In practice it often means buying the smallest death benefit the tax code will tolerate for a given premium — which is a strange thing to do with a life insurance contract if you also have a real protection need.
The second fair point: early-year costs are genuinely punishing. Mortality charges, administrative fees and surrender charges mean the first several years look poor on any honest ledger, and an adviser who glosses over that is managing your emotions rather than your money.
What the criticism misses is that the alternative instinct — underfund to be safe — has its own failure mode. A policy funded too thinly may not survive rising cost of insurance decades later. There is a sustainable band, and finding it is the actual job.
A great IUL is engineered. A bad IUL is sold.
The Parameters That Decide Your Result
MEC Limits and the 7-Pay Test
Under IRC 7702A, a policy becomes a modified endowment contract if cumulative premiums in the first seven contract years exceed a calculated limit. No single number applies across all policies — it depends on age, death benefit and carrier assumptions.
A material change to the death benefit can restart the 7-pay clock. Exceeding the limit changes how loans and withdrawals are taxed permanently, so any correction should run through the carrier and a qualified tax professional, fast.
Premium Amount, Duration and Consistency
A sustainable planned premium matters more than a large one-time contribution. Front-loading, reduced funding, skipped payments or irregular business income all change how cash value accumulates and how long the policy stays in force.
Before committing to a pattern, ask for an illustration that explicitly labels its assumptions — crediting rate, premium schedule, death benefit option — so you know what you are comparing.
Charges and Surrender Values
Premiums do not flow entirely into cash value. Mortality charges, administrative fees and rider costs reduce early values. When comparing illustrations, look at guaranteed cash value rather than only projected; surrender value and break-even timing; and non-guaranteed values under multiple crediting scenarios.
Crediting Mechanics
Cap sets the maximum credit for a period. Participation rate sets the share of index movement used. Spread is subtracted from index growth. Floor is the minimum index-account credit, often 0%.
The floor protects against a negative index credit. It does not eliminate ongoing charges or ensure cash value holds steady in a given year. The policy does not invest in the index; crediting is a formula applied to account value.
Zero is your hero in a down year — but the floor applies to the credit, not to the charges.

Loans, Withdrawals and Lapse Risk
Policy loans reduce cash value and the death benefit, accrue interest, and can create tax consequences if the policy lapses with debt outstanding. Under IRC 72(v), a MEC distribution — including certain loans — can trigger a 10% additional tax on the taxable portion before age 59½, with exceptions.
Some carriers offer an overloan protection rider, but activation conditions are typically restrictive: a minimum policy year, a minimum owner age. Do not assume a rider protects a loan strategy planned for your 50s if it does not activate until your 70s. Read the trigger, not the name.

Stronger Fit
- A genuine permanent insurance need, stable surplus cash flow, insurability and a long horizon — all four, not three
- High-income professionals, executives, business and practice owners
- Households that have already funded higher-priority savings and want another source of retirement liquidity
- Late-start high earners deserve a closer look specifically: a shorter runway, higher cost of insurance and less time to absorb early charges. That does not rule out an IUL. It means the funding math has to be realistic rather than optimistic.
Weaker Fit
This strategy is not appropriate for everyone. Caution is warranted if:
- Income is unstable or unpredictable
- Emergency savings are thin or nonexistent
- High-interest debt is the bigger priority
- The time horizon is short
- There is no actual permanent insurance need — buy term
- You could not tolerate early surrender losses
Evaluate this alongside your other options, not instead of them: an employer match, qualified accounts, Roth strategies, taxable investments, and term insurance where that coverage simply fits better.
| Option | Best fit when... |
|---|---|
| Term life insurance | Affordable, temporary protection is the priority |
| Whole life insurance | Guarantees and predictable cash value matter more |
| Traditional investments | Liquidity, simplicity or uncapped market exposure is the goal |
| Qualified plans / Roth accounts | Tax-advantaged retirement space is not yet maxed |
Risks to Understand Before You Fund
- Chasing the maximum illustrated premium instead of completing the needs analysis is the most common error in this category.
- Comparing projected cash value only, while ignoring guaranteed values and charges, hides the real cost.
- Funding above the approved limit without confirming available MEC room is irreversible.
- Displacing an employer match, emergency fund or needed term coverage with an IUL is a downgrade dressed as an upgrade.
- If cash value is lower than expected, diagnose the cause: lower credited interest, charges, missed premiums, loans or a funding pattern that drifted from the design.
- If premiums become unaffordable, request an in-force illustration before reducing payments, changing benefits or surrendering. Those actions are easier to understand on paper than in hindsight.
- If the policy is near lapse or carries a large loan, review it with the carrier and a tax professional immediately. The loan is not the problem; the unmanaged loan is the problem.
Find Out Where You Actually Stand
This starts with the Tax-Free Wealth Blueprint Fit Review. If you earn $150K+ and want a max-funded design built in the right order, we document the protection objective first, size the death benefit to the need, model your specific non-MEC ceiling, compare at least two designs across carriers, and stress-test the premium against a weak year rather than a strong one. Sometimes the answer is a higher death benefit with adjusted funding, a term rider, a lower sustainable premium, or a different tool entirely. If IUL does not fit, we will tell you that too.
Frequently Asked Questions
How much should I put into life insurance?
Life insurance is purchased with premiums, not invested like a brokerage account. The right amount depends on your protection need, sustainable cash flow, existing retirement priorities, health and policy design. There is no universal figure.
Can you have more than one IUL?
Yes. Multiple policies are possible, but combined death benefit, financial justification, underwriting and MEC limits all need review to confirm the additional coverage serves a legitimate purpose.
Can I sell my IUL policy?
You may surrender, exchange under Section 1035, or sell through a life settlement, depending on eligibility and state rules. Expect possible tax consequences and proceeds well below the death benefit. Get licensed financial and tax guidance first.
What is the right funding duration?
Long enough to carry the policy through rising cost of insurance, and short enough that you can realistically sustain it. Most designs assume a decade or more of funding. Model it against your income, not your intentions.
What if my income drops after I start?
Request an in-force illustration before changing anything. Reducing premium, lowering the death benefit and taking a loan all have different consequences, and the right move depends on where you are in the surrender schedule and the 7-pay window.
Does a max-funded design always beat a conventional one?
No. A max-funded design maximises cash value efficiency at the cost of protection headroom and funding flexibility. If your real need is coverage, a conventional design is the better contract.
Sources
- LIMRA — 2025 Insurance Barometer Study
- 26 U.S.C. § 7702A — Modified endowment contract defined
- 26 U.S.C. § 72 — Annuities; certain proceeds of endowment and life insurance contracts
- NAIC — Life Insurance Illustrations
Disclosure: This article is educational and is not personal tax, legal or investment advice. Indexed universal life is life insurance first. Underwriting outcomes, carrier rules, product terms and state availability vary and must be confirmed before applying; no approval can be guaranteed in advance. Illustrated values are not guarantees; actual results depend on policy terms, crediting, costs and funding. Any potential tax-advantaged access depends on the policy being properly structured, funded and managed. Actual results depend on policy design, carrier, crediting options, caps, participation rates, expenses, funding and ongoing management. This strategy is not appropriate for everyone. Policy loans and withdrawals reduce cash value and the death benefit, and can create tax consequences if the policy lapses or becomes a modified endowment contract. Consult your own tax, legal and financial professionals for advice specific to your situation.
And remember, it's not what you earn, it's what you keep… enjoy the ride.